What is the scope and industry significance of the Military Reconnaissance Market?
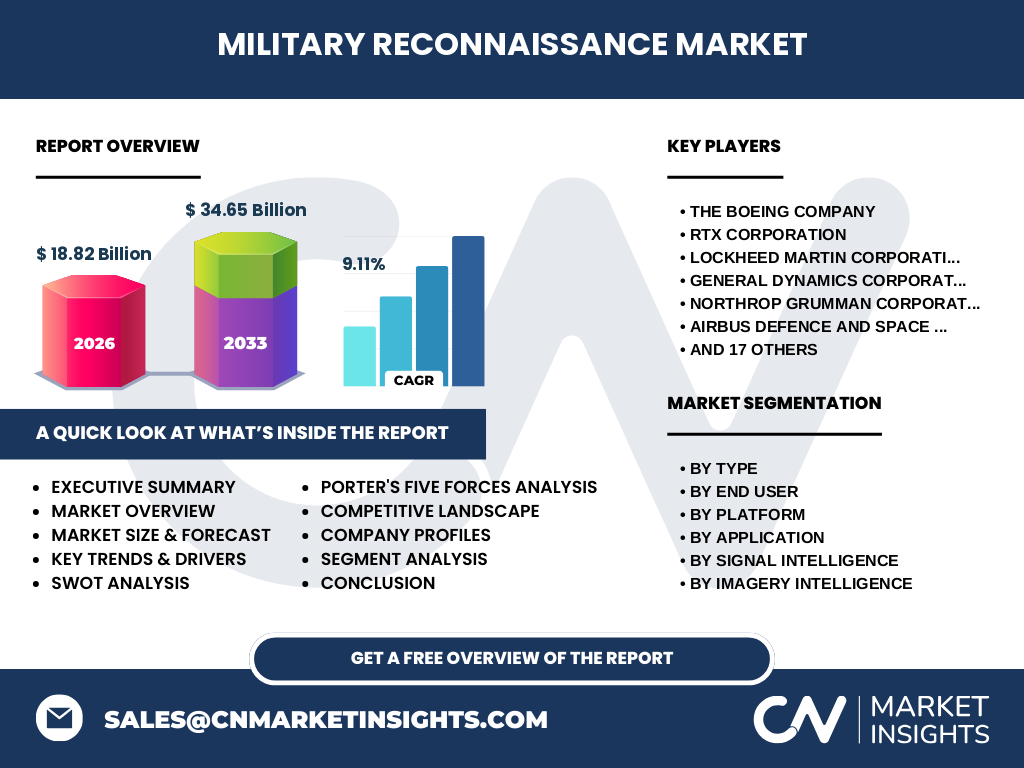
Our analysis indicates that the Military Reconnaissance Market is valued at 18.82 Billion in 2026, driven by rising geopolitical friction. This sector encompasses advanced intelligence-gathering frameworks deployed by aerospace primes and defense agencies worldwide to secure tactical superiority.
Key market drivers, restraints, challenges, and opportunities shaping the sector
The market is propelled by a 9.11% CAGR, pushing values toward 34.65 Billion by 2033. Supply chain bottlenecks for rare-earth elements constrain hardware production, yet opportunities in autonomous Signal Intelligence platforms provide lucrative growth avenues for agile defense contractors.
Emerging trends and growth patterns in the Military Reconnaissance Market
The shift toward real-time multi-INT fusion is redefining operational tempo. Industry trends highlight increased deployment of Synthetic Aperture Radar Imaging Analysis and commercial constellations by innovators like Planet Labs PBC, reducing reliance on legacy, vulnerable sovereign assets.
COVID-19 impact analysis and the post-pandemic recovery trajectory
The pandemic disrupted titanium and carbon composite supply chains, stalling hardware rollouts for manned platforms. However, defense digitization accelerated dramatically post-crisis, creating a resilient recovery trajectory favoring resilient software-defined surveillance architectures.
Competitive Benchmarking: Major players and strategic dynamics
Market concentration remains moderate to high, anchored by primes like RTX Corporation, Lockheed Martin, and Northrop Grumman. These giants leverage vertically integrated portfolios, competing fiercely with software disruptors like Palantir for lucrative DoD intelligence modernization contracts.
Executive Summary of the Military Reconnaissance Market industry trends
Our comprehensive report reveals a robust market expanding from 18.82 Billion in 2026 to 34.65 Billion by 2033. Strategic investments in AI-driven Imagery Intelligence remain the primary differentiator for market leaders navigating complex global threat landscapes.
Market forecast trajectory from 2027 to 2033
The data projects a steady 9.11% CAGR throughout the forecast window. By 2033, market expenditure will reach 34.65 Billion, heavily reinforced by escalating cross-border tensions demanding continuous, borderless space and aerial tracking solutions.
Segmentation Analysis by Type, End User, Platform, and Application
The market splits across Signal, Imagery, Electronic, and MASINT types. End users span Army, Navy, Air Force, and agencies utilizing UAVs, satellites, and ground vehicles for surveillance, targeting, and early warning applications.
Regional market analysis and geographic performance distribution
North America dominates baseline consumption due to high defense outlays, while the Asia-Pacific region exhibits the fastest expansion rate. Localized maritime disputes in the South China Sea drive heavy investments in naval and airborne reconnaissance assets.
In-depth regional review of key defense hubs
European markets focus on eastern flank deterrence, boosting demand for communications interception and radar tracking. Meanwhile, Middle Eastern procurement emphasizes border surveillance systems supplied by international leaders like Elbit Systems.
Company profiles and strategic positioning of leading defense contractors
Firms like BAE Systems plc and Thales Group leverage strong transatlantic footprints to secure avionics and electronic warfare contracts. Concurrently, specialized players like AeroVironment dominate tactical UAS niches, balancing the aerospace ecosystem.
Porter's Five Forces analysis of competitive intensity
Threat of new entrants is low due to stringent military qualification standards and high capital expenditure requirements. However, buyer power is moderately high, as major governments dictate strict compliance and cost-plus contract terms.
SWOT analysis of the global reconnaissance sector
Strengths lie in unmatched sensor fidelity and AI analytics; weaknesses involve vulnerability to electronic jamming. Opportunities abound in commercial space-based SAR, while regulatory export controls (ITAR) remain a persistent threat.
Value chain analysis from raw materials to end-users
The value chain originates with raw semiconductor and alloy suppliers, flowing through sensor manufacturers like HENSOLDT, integration primes like Boeing, and ultimately serving defense intelligence agencies operating in the field.
Investment insights and high-potential areas
Investors should target early-stage firms specializing in Nuclear Signature Detection and automated geospatial mapping. These niches align directly with surging government budgets dedicated to asymmetric threat mitigation.
Conclusion and key takeaways for stakeholders
Sustained by a 9.11% CAGR toward 34.65 Billion by 2033, the sector offers exceptional growth. Success demands pivoting from hardware-centric sales to integrated, software-first intelligence ecosystems.
Research methodology for baseline estimations and triangulation
Our research combines primary interviews with defense attachés and procurement chiefs, cross-referenced with trade registries, budgetary filings from NATO allies, and macroeconomic indicators to ensure absolute accuracy.
Scope of the report, coverage parameters, and operational limitations
This report covers global military reconnaissance expenditures from 2026 to 2033. Limitations include restricted access to classified black-budget programs, focusing strictly on publicly disclosed contracts and verified market data.
Recent developments, partnerships, and strategic product launches
Recent industry momentum features major joint ventures in quantum radar development and high-altitude pseudo-satellite (HAPS) trials by companies like Airbus Defence and Space, signaling a technological shift toward persistent, stratospheric observation.